Your Rent Can Help You Buy a House: How On-Time Rent Counts Toward a Mortgage
By Daniel Barash, REAL Broker AZ, LLC | Updated November 7, 2026
Short answer: Yes, the rent you pay as a tenant can help you qualify for a mortgage. Fannie Mae's and Freddie Mac's underwriting systems can spot 12 months of on-time rent of $300 or more in your bank statements, and FHA lets lenders count a clean 12-month rent record for first-time buyers. A newer credit score, VantageScore 4.0, can also factor in rent, but only if your rent gets reported to the credit bureaus.
This matters most if you're in your late 20s or 30s, pay rent every month without fail, and have a thin credit file: maybe one credit card, no car loan, no student loans. Here's how each path works, what it takes, and what to ask a lender.
Does paying rent on time help you get a mortgage?
It can. Fannie Mae, Freddie Mac and FHA have each had a way to give you credit for on-time rent since 2021 or 2022. They work differently. Fannie Mae and Freddie Mac read your bank statements, Fannie Mae also checks your credit report, and FHA has your lender document your rent by hand. Your credit score itself only changes if your rent is reported to the credit bureaus.
When Fannie Mae announced its version in August 2021, it said fewer than 5% of renters had rent payments showing on their credit reports. Then-Federal Housing Commissioner Julia Gordon put the logic simply when FHA added its version in 2022: "If you're regularly paying your rent on time, that's a good indication you will also pay your mortgage on time."
How does Fannie Mae use your rent history?
Fannie Mae's Desktop Underwriter (DU), the system most lenders run conventional loans through, looks for 12 months of rent payments in a bank account report you give the lender permission to pull, or in rent history already on your credit report. Fannie Mae says this is "a positive-only change," so missing or irregular rent in the data isn't counted against you.
Fannie Mae turned this on September 18, 2021. According to its July 2026 FAQ, at least one borrower on the loan needs to:
- Have rented for at least 12 months, with rent of $300 or more a month (12 consecutive payments if it's coming from your bank data)
- And have no mortgage on their credit report, a limited credit history, or no credit score
You don't have to be the only borrower who qualifies, and it doesn't change your credit score. It only feeds into DU's overall risk decision. Fannie Mae says more than 21,000 mortgage applications got a better DU recommendation from rent payments in bank statements between September 2021 and May 2026.
When the program launched, then-CEO Hugh R. Frater said, "Many renters believe they will never be able to buy their own home because of insufficient credit." Fannie Mae's research at the time found that 17% of recent applicants who hadn't owned a home in three years and didn't get a favorable DU decision could have been approved if their rent history had been counted.
How does Freddie Mac use your rent history?
Freddie Mac's Loan Product Advisor (LPA) can count 12 months of rent found in a bank account report for first-time buyers on a purchase loan. It has been available to lenders since July 10, 2022. Like Fannie Mae's version, Freddie Mac says it "may only positively affect" the LPA credit assessment.
Freddie Mac's rules are a little tighter than Fannie Mae's. Per its fact sheet:
- Purchase of a primary residence only
- At least one borrower with the rent history has to be a first-time buyer who will live in the home
- That borrower needs a usable credit score
- Rent of at least $300 a month for the most recent 12 consecutive months
- Payments must come out of your bank account. Checks and transfers like Zelle, Venmo or PayPal count. Cash doesn't.
Freddie Mac also runs a separate program on the apartment side. Since November 2021, it has helped owners of Freddie Mac-financed apartment buildings report on-time rent to all three credit bureaus "at no cost to renters." Fannie Mae has a similar pilot for properties it finances, using vendors such as Esusu, Jetty and Entrata.
Can on-time rent help with an FHA loan?
Yes, for first-time buyers. Since October 30, 2022, FHA has let lenders flag a positive rental history in its TOTAL Mortgage Scorecard, the system that scores FHA loans. It's narrower than the Fannie Mae and Freddie Mac versions, and late rent rules it out.
HUD Mortgagee Letter 2022-17 sets the requirements:
- A purchase loan, with at least one first-time homebuyer (no ownership interest in a home in the past three years)
- A minimum decision credit score of 620
- Rent of $300 or more a month for the previous 12 months, with all 12 payments on time ("paid within the month due")
- Your lease, plus proof: a landlord or property management company verification, 12 months of canceled checks, or 12 months of bank or payment app statements
If you rent from a family member, FHA wants the lease plus 12 months of canceled checks or bank statements.
What is VantageScore 4.0, and can it count your rent?
VantageScore 4.0 is a credit score that can include rent and utility payments when they're reported to the credit bureaus. As of September 9, 2026, every approved lender can use it for Fannie Mae and Freddie Mac loans. Lenders still choose between it and the older Classic FICO, so ask which one yours uses.
Here's the timeline, from the Federal Housing Finance Agency (FHFA), Fannie Mae and HUD:
| Date | What happened |
|---|---|
| July 8, 2025 | FHFA announced lenders could use VantageScore 4.0 or Classic FICO for Fannie Mae and Freddie Mac loans |
| April 22, 2026 | Limited rollout began; FHA said it would accept VantageScore 4.0 and FICO 10T |
| September 9, 2026 | VantageScore 4.0 opened to all approved Fannie Mae and Freddie Mac lenders (Fannie Mae Lender Letter LL-2026-06) |
| January 1, 2027 | FHA starts accepting VantageScore 4.0 for case numbers assigned on or after this date |
Details as of November 2, 2026, subject to change.
FHFA Director William J. Pulte said in April that the change is "helping millions of Americans who responsibly pay rent qualify for mortgages." VantageScore says its 4.0 model scores 33 million more people than traditional models.
The catch: VantageScore can only use rent the bureaus actually have. VantageScore's own consumer guide says the score "can factor in rental payment history if it's reported to the credit bureaus." If your landlord doesn't report, and you haven't signed up for a reporting service, your rent won't show up in any score. One thing nobody has published yet: how many Valley lenders have actually switched. Lenders can keep using Classic FICO, so the only way to know is to ask.
Which rent path fits your situation?
| Path | Loan type | Where rent comes from | Key requirements |
|---|---|---|---|
| Fannie Mae DU rent history | Conventional | Bank account report or credit report | 12 months at $300+; no mortgage on credit, limited credit or no score; misses don't count against you |
| Freddie Mac LPA rent history | Conventional | Bank account report | Purchase, primary home, first-time buyer, usable credit score, 12 months at $300+, no cash payments |
| FHA positive rental history | FHA | Lease plus landlord verification, checks or statements | Purchase, first-time buyer, 620+ score, all 12 payments on time |
| VantageScore 4.0 | Conventional now; FHA from January 1, 2027 | Credit bureaus | Rent must be reported; your lender has to use VantageScore 4.0 |
What should you do now to make your rent count?
Make every rent payment easy to prove and, if you can, get it onto your credit report. Then ask lenders which of these tools they actually use. A year of clean, traceable rent is the base for all four paths.
- Pay by bank transfer, check or your landlord's online portal. Freddie Mac doesn't count cash, and FHA needs paper proof. Paying from the same account every month makes the pattern easy to spot.
- Pay on time, every month. Fannie Mae and Freddie Mac ignore misses, but FHA's version requires all 12 payments on time.
- Ask your landlord or property manager whether they report rent to the credit bureaus. Some apartment communities and property management companies offer it, sometimes through the Fannie Mae or Freddie Mac programs. That goes for single-family rentals too, so if a property manager handles your house, send them a quick email. If the answer is no, third-party rent reporting services exist. Read the fees and terms first.
- Keep your lease and a year of statements handy. Your lender may ask for them.
- Ask each lender two questions: "Will you run my file with DU or LPA rent history?" and "Do you use VantageScore 4.0 or Classic FICO?" Their answers can change which loan works best.
Talking to more than one lender also tends to get you a better rate. I covered that, plus buydowns and assumable loans, in How to Get a Lower Mortgage Rate in Phoenix in 2026.
What other help is there for first-time buyers in the Phoenix area?
Down payment assistance can stack with these rent tools. Two programs Valley buyers ask about most are the City of Phoenix's Open Doors program and Arizona Industrial Development Authority's Home Plus. Each has income limits and a required homebuyer class, and funding can change.
- City of Phoenix Open Doors: up to 10% of the purchase price for down payment and closing costs, as a 0% deferred loan with no monthly payments that's forgiven after an affordability period of up to 15 years. It's for first-time buyers earning at or below 80% of area median income, buying inside Phoenix city limits, with a purchase price cap of $470,250. Buyers must take an eight-hour homebuyer class and get one-on-one counseling from a HUD-approved agency. City of Phoenix homeownership programs
- Home Plus (Arizona Industrial Development Authority): up to 4% for down payment and closing costs. The forgivable option is a no-interest, no-payment second loan forgiven after five years; it has to be repaid if you sell or refinance before then. Borrower income can't exceed $155,386 (as of April 6, 2026), and one borrower needs a homebuyer education course. Home Plus program details
Program details as of November 2, 2026, subject to change. Check with the program or a participating lender for current funding and eligibility.
Frequently asked questions
Does rent count toward a mortgage?
It can. Fannie Mae and Freddie Mac can count 12 months of on-time rent of $300 or more from your bank statements, and FHA can count a fully on-time 12-month rent history for first-time buyers. Rent reported to the credit bureaus can also feed into VantageScore 4.0.
Do I need a credit score to buy a house?
Not always, but it makes things easier. Fannie Mae's rent history feature is open to borrowers with no credit score. Freddie Mac's version needs a usable score, and FHA's needs at least a 620. Ask a lender what your options are if you have no score at all.
Does late rent hurt me?
Not in Fannie Mae's or Freddie Mac's rent features; both are positive-only and don't count missed payments against you. FHA is different: any late payment in the last 12 months means the positive rent history flag can't be used. Late rent that a landlord reports to the credit bureaus can still hurt your credit score.
How many months of rent history do I need?
Twelve. Fannie Mae, Freddie Mac and FHA all look at the most recent 12 months, with rent of at least $300 a month.
Does my landlord have to report my rent?
Only for it to show up in a credit score like VantageScore 4.0. Fannie Mae's and Freddie Mac's tools can find your rent in your bank statements without any landlord reporting.
Want to see where you stand?
If you've been renting and wondering whether you're closer to buying than you think, I'm happy to look at the numbers with you. No pressure, and no commitment. I can introduce you to lenders I trust who can tell you whether DU or LPA rent history or VantageScore 4.0 helps in your case. Call or text me at 480.906.3831.
For current rates and example payments, see my October 2026 mortgage rates post. And if you're looking for something to do this month, here are things to do in Phoenix in November.
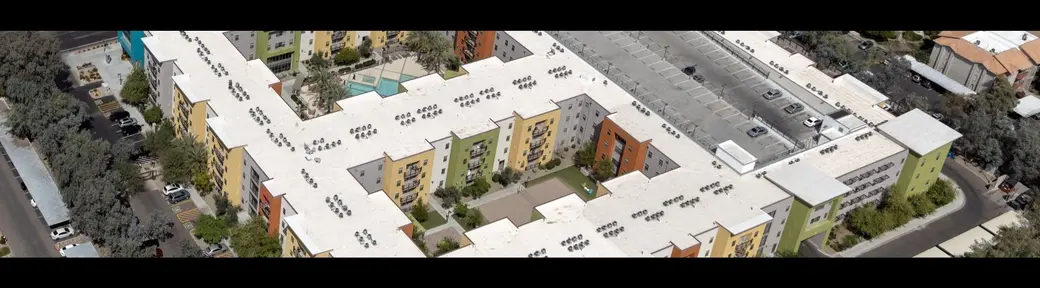
This is general information, not legal, tax, lending or financial advice. Talk with a licensed lender about your situation. Loan program rules and score policies as of November 2, 2026, subject to change. Header photo: Aerial view of apartment buildings near Arizona State University in Tempe, March 26, 2018, by Carol M. Highsmith, cropped. Carol M. Highsmith Archive, Library of Congress, Prints and Photographs Division.
Sources
- Fannie Mae: Positive rent payment reporting (data through May 2026)
- Fannie Mae: Positive Rent Payment History FAQs (updated July 2026)
- Fannie Mae news release, Aug. 11, 2021
- Freddie Mac news release, June 29, 2022
- Freddie Mac: Rent payment history in LPA fact sheet
- Freddie Mac Multifamily: Credit building through rent reporting
- Fannie Mae Multifamily: Positive rent payment reporting
- HUD news release 22-187, Sept. 27, 2022
- HUD Mortgagee Letter 2022-17
- FHFA: Credit scores (updated Oct. 2, 2026)
- FHFA news release, April 22, 2026
- Fannie Mae Lender Letter LL-2026-06, Sept. 9, 2026
- FHFA: VantageScore 4.0 implementation FAQ
- HUD: FHA Alternative Credit Scores Prep Guide
- NAR: FHA sets implementation date for alternative credit score models, Sept. 15, 2026
- VantageScore: FHFA and HUD announcement, April 22, 2026
- VantageScore: Top 10 consumer questions, July 28, 2025
- City of Phoenix: Homeownership opportunities (Open Doors)
- Arizona Industrial Development Authority: Home Plus
About the author: Daniel Barash has spent 10 years in Phoenix-area real estate and works with buyers and sellers across Tempe, Chandler and the greater Phoenix area with REAL Broker AZ, LLC.
Daniel Barash | REAL Broker AZ, LLC | 480.906.3831
Categories
Recent Posts
"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "